Loan consolidation, simplified
1 EMI. 1 Date. 1 Loan. Zero Stress.
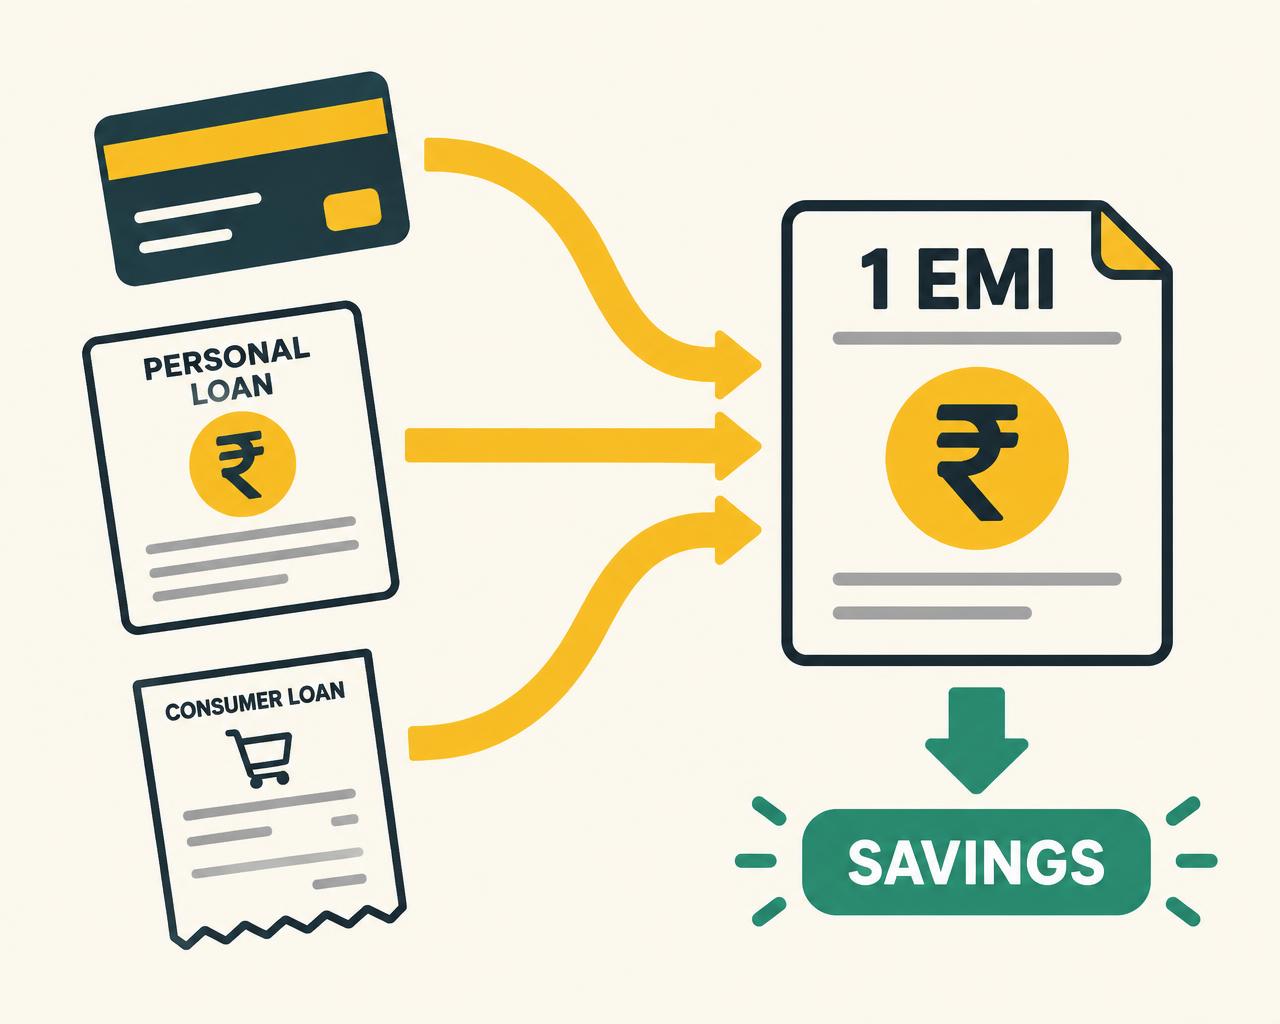
Merge your Credit Cards, Personal Loans, App Loans & other EMIs into 1 EMI with an extended tenure, starting from @9.99% p.a.
Just enter your total EMI sum & average rate of interest below.
*Estimate uses the same 5-year repayment term at your current rate and at 9.99% p.a. Fees are excluded; your actual offer may differ.
Get My Savings OfferGet Best Savings Offer on your Existing Loan
01 / Why consolidate
Many loans?
One simple EMI.
Credit card bills, personal loans, consumer loans — paying each one separately is stressful and expensive. Bring them together into one loan at a lower rate, pay a single EMI on a single date, and keep the savings, month after month, for years.
Interest rate starting from
9.99%
p.a. · Subject to eligibility and lender terms
One date to remember
No more juggling payment dates.
Savings that grow
A smaller EMI adds up over the years.
02 / Live Example
Same loan. Lower rate.
Real savings.
Live example: a ₹25,000 monthly EMI at 24% p.a., recalculated at 9.99% p.a. over the same five-year term.
| What changes | Current loan | At 9.99% p.a. |
|---|---|---|
| Monthly EMI | ₹25,000 | ₹18,460 |
| Interest rate | 24% p.a. | 9.99% p.a. |
| Repayment term | 60 months | 60 months |
| Monthly savings | — | ₹6,540 |
| Savings over 5 years | — | ₹3,92,400 |
Example calculation only, excluding fees. Your actual offer depends on eligibility and lender terms. A longer term can lower the EMI but increase total interest — always compare the full repayment cost.
More money left each month
A lower-rate offer can free up a part of your monthly income for the things that matter.
One EMI instead of many
Eligible card bills and loans become a single repayment on a single date.
Savings that add up
A smaller EMI every month grows into a large saving over the full loan term.
03 / See the difference
Merge many EMIs into one — and watch the savings.
A borrower paying ₹25,000 a month at 24% p.a. could see the same five-year repayment look like this at a lower rate.
Monthly repayment at 24% p.a.
₹25,000
High-rate EMIs leave little room for savings, plans or emergencies.
04 / Is this you?
If any of these sound familiar, consolidation could help.
These are reasons to compare your options — not a promise of eligibility or savings.
Too many EMIs?
Credit card bills and loan EMIs on different dates are hard to track — and easy to miss.
EMIs eating your salary?
A big share of your income goes into repayments, leaving little for everyday life.
Paying only card minimums?
The remaining balance keeps growing at a high interest rate, month after month.
Stuck at a high rate?
Your current loan charges more than the balance transfer offers available today.
Offers from trusted names
Compare offers across
leading banks & NBFCs.

TATA CAPITAL

BAJAJ FINSERV

SMFG India Credit

ICICI Bank
Kotak Mahindra

IDFC FIRST Bank
YES BANK

Poonawalla Fincorp
Lender names and logos shown for reference only. Inclusion does not confirm a partnership or an available offer.
05 / How Rupilo works
From many EMIs to one EMI — in 4 simple steps.
01
Check your savings
Use the EMI Savings Calculator above to see how much you could save every month at a lower rate.
02
Fill in your details
Share your employment type and mobile number in the form above — it takes barely a minute.
03
Get FREE advisor help
Our financial advisor calls you, compares the best offers across banks, and plans your consolidation.
04
Move to one EMI
Merge your loans into a single EMI at a lower rate — and start saving from the very first month.
Before you decide
One EMI. Zero hassle.
Honest numbers.
Our goal is simple: replace your many EMIs with one lower, hassle-free EMI from a trusted bank or NBFC — and turn the monthly difference into long-term savings. We help you compare offers, explain the full cost, and never rush your decision.
Calculator results and examples are estimates, not approval or guaranteed savings. Rates starting at 9.99% p.a. and savings of up to 50% depend on eligibility and lender terms. Always compare the APR, fees and total repayment in your final offer.
Indian business & financial publications · Names shown for reference, not an endorsement.